7月以来美股半导体板块经历大幅波动,反映出市场对AI资产定价方式的根本性转变1。"闭眼买AI"的投资阶段已经过去,市场心态从无条件看好转向要求更多商业回报证据1。
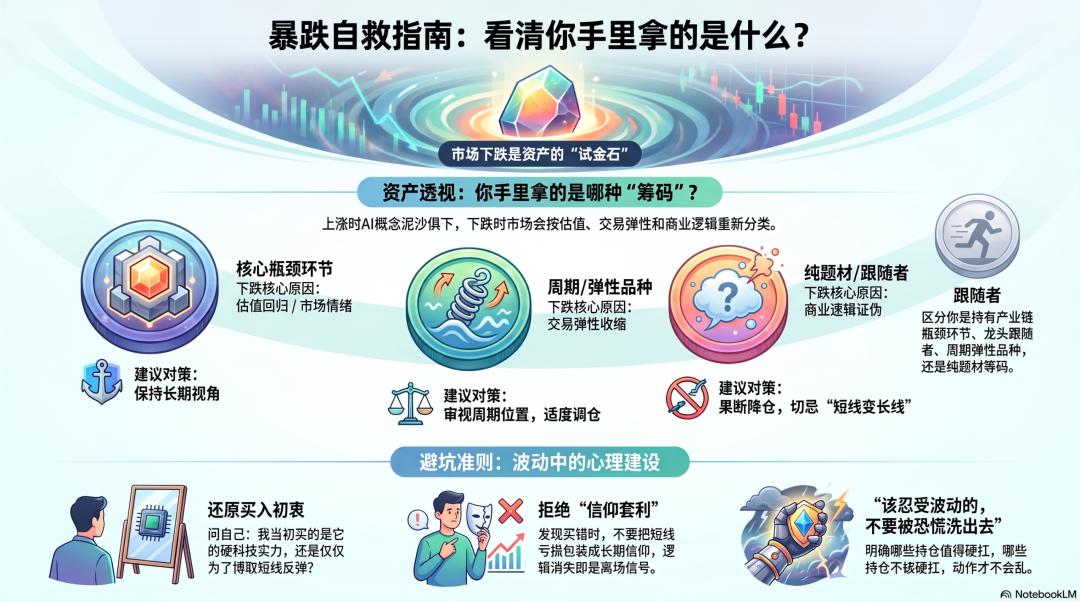
虽然AI需求仍然保持强劲,但成长股的核心交易逻辑已发生改变,关键在于是否能带来"比预期更好"的表现1。此前云厂商资本支出(Capex)的上修曾是市场利好,如今却成为需要解答的问题——投资者开始要求看到这些AI投入转化为实际商业回报的证据1。为适应市场变化,投资者需要重新分类持仓资产,将AI半导体相关投资划分为四个类型:收税型资产、卖铲型龙头、周期弹性资产和纯叙事资产1。
The semiconductor sector in U.S. markets has experienced significant fluctuations since July, prompting investors to fundamentally reconsider how artificial intelligence assets should be valued 1. The era of indiscriminate enthusiasm for AI investments has largely concluded, as market sentiment has shifted from unconditional optimism toward demanding concrete evidence of commercial returns 1.
While demand for AI technology remains robust, the dynamics governing growth stock valuations have changed materially 1. Investors now require proof that performance exceeds expectations rather than simply meeting baseline forecasts. This shift has transformed cloud infrastructure providers' increased capital expenditures from a positive signal into a critical question mark 1. The market is demanding visibility into tangible business returns generated by these substantial AI infrastructure investments 1.
To navigate this changed landscape, market observers have categorized AI semiconductor-related holdings into four distinct asset classes: revenue-generating assets positioned to capture value, leading suppliers selling essential infrastructure, cyclical positions with earnings elasticity, and purely narrative-driven plays 1. This classification framework reflects the market's transition toward a more differentiated and critical assessment of the diverse competitive positions and business models within the artificial intelligence ecosystem 1.
评论
还没有评论,欢迎留下第一条。